If we only compare the step of "withdrawing from the receiving account to China," WorldFirst's settlement to Alipay is the fastest. The official statement says it can arrive in as little as 1 minute, and withdrawals are available 24/7, unaffected by weekends and holidays.
When withdrawing to domestic bank cards, LianLian Global's fast withdrawal, Airwallex's local clearing, and PingPong generally complete within minutes to a few hours during working hours. Payoneer's official standard is 1–2 business days.
However, many sellers feel that "arrival is slow," but the slowness is often not in the withdrawal step. A common situation is that the platform's payment to the receiving account is inherently slow, or the withdrawal is stuck in risk control review. First identify which stage is slow, then decide whether to switch platforms or add tools.
First Distinguish: "Arrival" Actually Has Two Stages
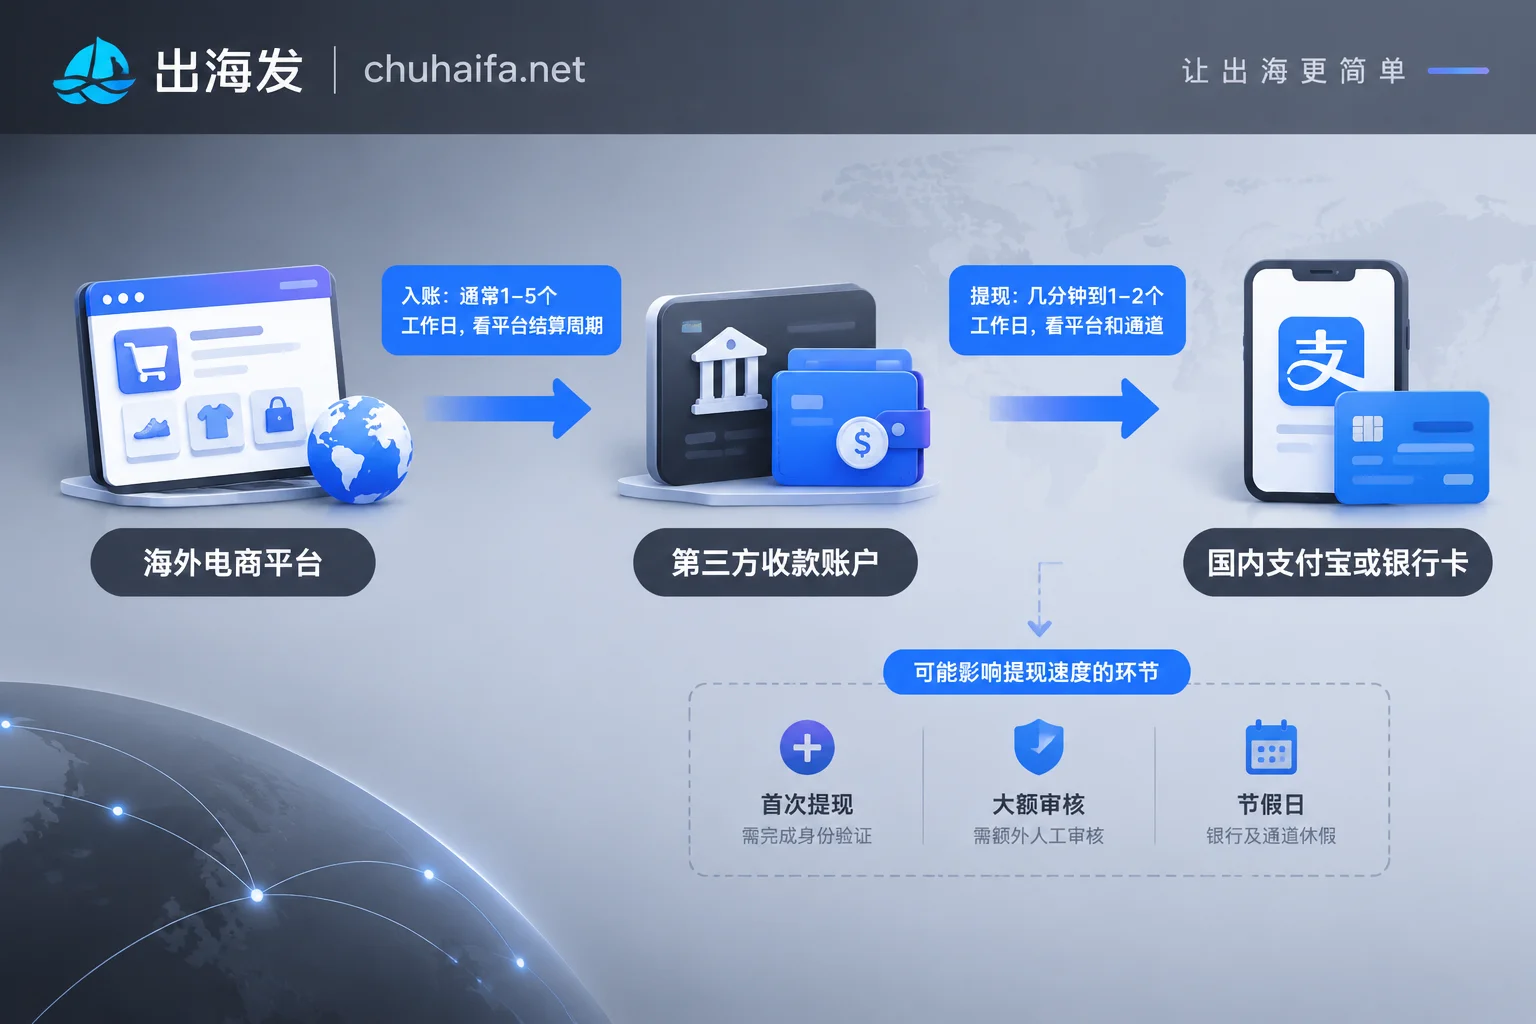
- Deposit: Platform or buyer payment → Third-party receiving account. Taking LianLian Global's explanation as an example, after mainstream platforms like Amazon and Shopee make payments, it usually takes 1–5 business days to enter the account. This stage mainly depends on the platform's settlement cycle and clearing path, and switching receiving platforms generally doesn't change much.
- Withdrawal: Settlement and withdrawal from receiving account → Domestic bank card or Alipay. The speed differences among providers are mainly in this stage.
The method to judge is simple: if the platform shows payment has been made, but it hasn't entered the receiving account for several days, the problem is in the first stage; if there is already money in the receiving account, but withdrawal hasn't arrived for half a day, then you need to compare the withdrawal speeds of various providers.
Withdrawal Speed Comparison of Major Receiving Platforms
| Platform | Withdrawal Destination | Fast Channel | Regular/Standard Time | Conditions Affecting Speed |
|---|---|---|---|---|
| WorldFirst | Alipay (same name or corporate account) | As fast as 1 minute, 24/7 | — | Direct settlement for major currencies |
| WorldFirst | Domestic bank card | Regular settlement withdrawal initiated before noon on business days, T+0 same-day arrival | Foreign currency cross-border wire transfer usually 1–5 business days | Initiation time, withdrawal method |
| LianLian Global | Domestic bank card | RMB fast/premium withdrawal, fastest 5 minutes–2 hours during working hours | Regular withdrawal T+1 | Whether during working hours |
| Airwallex | Domestic bank account | As fast as 5 minutes to several hours | Standard 0–3 business days | Currency, receiving location, local clearing or SWIFT |
| PingPong | Domestic bank account | Usually 2 hours–1 business day during working hours | — | Also has "Light Year" for early access to payment |
| Payoneer | Domestic bank card | Actually mostly 2–24 hours | Official 1–2 business days | Bank working hours, weekends |
The above timeliness comes from various help centers and public statements. Fast channels usually have conditions on currency, amount, time period, or fees, and the actual display on the withdrawal page shall prevail. PingPong's timeliness description was published earlier, and Payoneer's actual timeliness comes from third-party compilation; it is recommended to verify these two on the official website before opening an account.
Why the Same Platform Is Sometimes Fast, Sometimes Slow
What affects arrival speed is often not the withdrawal technology itself, but compliance risk control and clearing paths. The following situations can significantly prolong the time:
- First withdrawal: Usually requires an extra round of verification.
- Store not authorized, transaction records not bound: The platform cannot verify the trade background, and withdrawal may be suspended, requiring supplementary materials.
- Large amount: Exceeding a certain limit may trigger anti-money laundering review.
- During holidays or non-bank working hours: Both domestic and foreign holidays count. Bank card channels are most affected, while 24/7 channels like WorldFirst to Alipay are less affected.
In these situations, switching platforms may not necessarily speed things up, because the new platform's first withdrawal also requires review.
How to Choose Based on Your Situation
Fund turnover mainly relies on Alipay: Based on existing information, WorldFirst settlement to Alipay is the fastest route, suitable for small teams and individual sellers who need money on weekends. The prerequisite is withdrawing to a same-name Alipay or corporate Alipay account.
Money must go to a bank card (corporate or personal): If withdrawing during business hours, LianLian Global fast withdrawal, Airwallex local clearing, and WorldFirst T+0 initiated before noon can basically arrive the same day. At this point, the difference of tens of minutes is not significant; what's more worth comparing is exchange rate spreads, withdrawal fees, supported store platforms, and currencies.
What's really lacking is the payment cycle: For example, Amazon's settlement cycle ties up money on the platform for two weeks, and no matter how fast the withdrawal is, it won't help. Products like PingPong's "Light Year" allow early access to payment when the platform pays out or the order is generated, essentially accounts receivable financing, which incurs fees. It is suitable when turnover is tight and gross profit can cover financing costs; the fee rate is subject to the official website.
Already using Payoneer: You don't necessarily need to switch platforms for speed. Just allow 1–2 business days, and don't initiate temporarily on Friday afternoon or before holidays. If customers or platforms only support Payoneer payments, there's no issue of choosing based on speed.
Additionally, which providers you can open and what type of account depends on where the company entity is registered and whether you're receiving platform payments or B2B foreign trade payments. For this part, you can refer to How to Choose Cross-Border Payment Platforms Based on Company Entity.
Practical Tips to Make Money Arrive Faster
- Complete store authorization and binding as soon as possible after opening an account, so that every deposit can be matched to the transaction source.
- For the first withdrawal, go through the process with a small amount to confirm that the payee information matches the account name.
- Before large withdrawals, prepare trade background materials such as contracts, invoices, and logistics documents in advance, so you can submit them the same day if requested.
- For withdrawals to bank cards, try to initiate in the morning on business days; withdraw money needed before holidays in advance.
There are still two things that existing information cannot clarify, and you need to ask the platform account manager directly: first, the limit for extremely large single transactions using instant arrival during holidays; second, how long it takes for payments from independent site acquiring channels like Stripe and Shopify Payments to reach the receiving account.
Next Steps
Once you've decided whether money goes through Alipay or bank card, and whether you need early access to payment, you can go to our site's Overseas Payment category and check the account opening conditions on each official website. If the money you receive is also used to pay for advertising and subscription tools, you can continue reading How to Pair Virtual Cards with Cross-Border Receiving Accounts.